From Cash Envelopes to an App: The Decisions That Keep the Discipline Intact
This post may contain affiliate links which might earn us money. Please read my Disclosure and Privacy policies here
Peeling twenties out of a grocery envelope stings in a way that tapping a card never will, and that sting is the whole point of cash envelope budgeting. MIT Sloan research suggests cards may even step on the gas by creating a craving to spend.
Take away the friction and most people spend more, faster, and barely notice. What most families fear about going digital isn't the tech itself; it's losing the friction that kept the whole system honest.
The good news is you can keep the discipline and pocket the convenience. You do have to make a few deliberate decisions on the way in, because the wrong app turns your envelopes into a spending diary.
Here's how to think through each choice.
Decide Whether You're Ready to Leave Cash Behind
Before you pick a tool, be honest about why the envelopes worked for you in the first place. If counting bills into a grocery envelope every Friday is what kept your family on track, ripping that habit out overnight is a bad move.
Plenty of households do better keeping cash for one or two high-risk categories, usually groceries and dining out, and moving everything else digital.
Ask yourself a few plain questions before you commit:
- Which envelope did you cheat on most? That's the category that needs the strongest guardrails in an app, not the loosest.
- Who else touches the money? A partner who never opened an envelope isn't going to open an app either. Pick a tool both of you will check.
- What's your fallback? If the app frustrates you in week two, do you go back to cash or push through? Decide now, not mid-argument.
Pick a Tool That Assigns Money Before It Tracks It
This is the decision that makes or breaks the whole transition. Most budgeting apps track spending after the fact and hand you a pie chart at the end of the month. That's a receipt collection, not envelope budgeting.
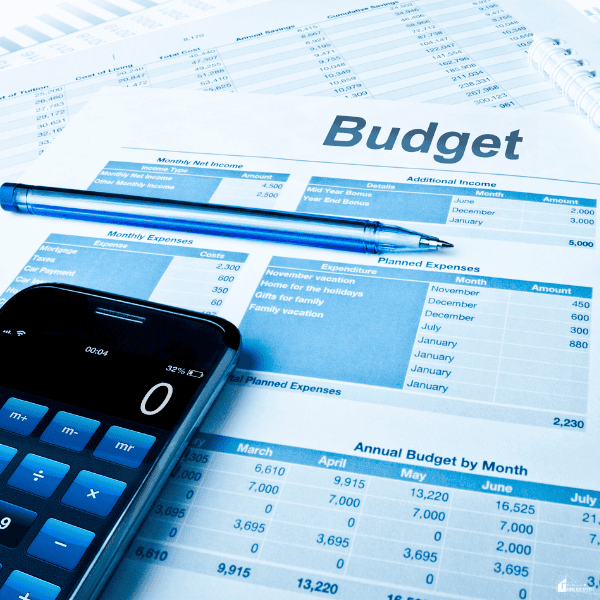
The apps that stand in for envelopes make you assign every dollar a job the moment it lands in your account. Groceries, gas, and the kids' activities each get a defined amount, funded up front. When an envelope hits zero mid-month, the app warns you before you swipe.
Tools like FinlyWealth are built around this assign-before-you-spend logic, with real-time budgets that show what's safe to spend right now, not what you already blew through last Tuesday.
When you're comparing options, look for three specific features: a way to fund categories from incoming pay, a live “safe to spend” number that updates as you swipe, and a rule for what happens when a category runs dry. Miss any one of those and the app is a tracker wearing a budget skin.
Choose How Strict the Guardrails Should Be
Cash envelopes are strict by default. When the envelope is empty, you physically can't spend more without going to another envelope and admitting the swap. Digital tools give you a spectrum, and you have to pick where you sit on it.
- Soft guardrails. The app warns you when you're close to a category limit but lets the transaction through. Good for disciplined spenders who want data, not walls.
- Hard guardrails. The card declines or the transfer is blocked when a category is empty. Closest to real envelopes, and the right call if you know you'll rationalize an overspend the moment you get the chance.
- Category swaps. The app makes you move money from another envelope before spending. This preserves the discipline of the cash system: you can still buy the thing, but only by consciously taking from something else.
Households moving over from cash almost always underestimate how much they leaned on the hard stop. Start stricter than you think you need. You can loosen the rules later if the friction feels excessive.
Confirm the Card and the App Actually Talk to Each Other
This one trips up more households than any other piece of the setup. You build beautiful envelopes in your budgeting app, then swipe a card that has no idea those envelopes exist. Transactions land in the app a day or two later, categorized wrong, and you're back to reconciling instead of budgeting.
The cleaner setup is a card that feeds spending into the same system that holds the envelopes, in real time. That way the grocery envelope updates the moment you leave the store, and the number on your phone is a number you can trust.
If you're stitching together separate tools, test the sync for two weeks before you commit.
Decide What to Do When You Overspend
You'll overspend. Everyone does. The decision worth making in advance is what happens next, because “I'll figure it out” is how people slip out of a budgeting app by month three.
Two rules cover most of it. First, the money has to come from another named envelope, not from some vague “we'll cover it later” pile. If groceries went over this week, the overage comes out of dining or entertainment today, in the app, before you close it.
Second, if the same envelope goes over three months in a row, the envelope is wrong, not you. Raise it, cut something else to fund it, and move on. Moving to an app isn't about running a tighter budget; it's about running the same discipline with less friction and better information.